Key Points
● Core Retail Channel: Convenience stores accounted for 92.9% of U.S. OTP sales and 82.9% of cigarette sales in 2025, according to NIQ data provided by NACS.
● Category Shift: Over the latest 52 weeks, cigarette dollar sales in convenience stores fell 2.5%, while OTP sales were flat. Combined, the two categories were down 1.7%.
● Smokeless Alternatives: NACS said its Smokeless Tobacco Alternatives subcategory, which includes nicotine pouches, grew 22.4% in dollar sales and 15.2% in unit sales.
● Retail Margins: NACS's CSX database puts gross margin at 14.86% for cigarettes and 29.85% for OTP. Rapanick said aggregate nicotine gross profit is growing.
2Firsts
WASHINGTON, Oct. 2, 2026 —
Cigarette dollar sales in U.S. convenience stores fell 2.5% over the latest 52 weeks, while other tobacco products, or OTP, were flat and a subcategory that includes nicotine pouches continued to post double-digit growth, according to NIQ data provided by NACS to 2Firsts.
NACS said its Smokeless Tobacco Alternatives subcategory rose 22.4% in dollar sales and 15.2% in unit sales over the same period. When cigarette and OTP sales are combined under what NACS increasingly views as a broader "nicotine" category, dollar sales were down 1.7% year over year.
Ahead of the 2026 NACS Show in Las Vegas, 2Firsts interviewed Chris Rapanick, managing director of research at NACS, about what the data and retailer feedback show about changes in the U.S. tobacco and nicotine market.
The NACS Show will run Oct. 6-9, with the expo open Oct. 7-9. NACS represents the convenience and fuel retailing industry and maintains industry research and benchmarking programs covering sales, operations and profitability. The United States has 151,975 convenience stores, according to the 2026 NACS/NIQ industry store count.

Convenience Stores Remain the Core Nicotine Retail Channel
Convenience stores remain the dominant U.S. retail channel for cigarettes and OTP, Rapanick said.
According to NIQ data provided by NACS, 92.9% of OTP sales and 82.9% of cigarette sales in the United States in 2025 took place through the convenience channel.
"NACS has begun to view cigarettes and other tobacco products (OTP) in aggregate as 'nicotine,'" Rapanick said.
NACS uses OTP as a broad convenience-retail grouping for products outside cigarettes. Its current category guide labels the umbrella category "Other Tobacco/Nicotine Products" and includes traditional smokeless tobacco, cigars, vaping products, nicotine pouches and other products. Nicotine pouches fall within the Smokeless Tobacco Alternatives subcategory.
Rapanick said most of the recent growth in OTP has come from nicotine pouches and other alternative forms of nicotine delivery, while cigarettes have remained on a general downward trend.
"Nicotine shoppers are some of the most loyal to our channel, often shopping at our stores daily," he said.
He also pointed to polyuse among cigarette consumers. OTP can provide additional usage opportunities in situations where cigarette smoking is not possible, Rapanick said.
Smokeless Alternatives Grow as the Broader Category Contracts
Over the latest 52 weeks, cigarette dollar sales in convenience stores declined 2.5%, while OTP sales were flat, according to the NIQ figures provided by NACS. Unit counts declined in both categories.
Combined cigarette and OTP sales — the broader category NACS describes as nicotine — were down 1.7% year over year.
Performance within OTP varied sharply. Smokeless Tobacco Alternatives grew 22.4% in dollar sales and 15.2% in unit sales over the same period. NACS defines the subcategory to include nicotine pouches as well as several other smokeless alternatives.
The broader convenience market has also been under pressure. Rapanick said NIQ data showed total convenience-channel sales down 1.3% over the latest 52 weeks. NACS's CSX Convenience Benchmarking Database showed roughly 1,000 fewer in-store transactions per store each month, or about 30 fewer transactions a day.
Rapanick said the operating environment had become particularly challenging after March 1.
U.S. gasoline prices rose sharply around the same period. NACS reported on March 5 that retail gasoline prices had increased about 20 cents per gallon in two days. The association said rising fuel prices tend to squeeze fuel retailers' margins while leaving customers with less money to spend inside stores.
Higher OTP Margins Reshape Retail Economics
NACS's CSX database puts gross margin at 14.86% for cigarettes, compared with 29.85% for OTP, according to Rapanick.
He said the database is showing a move from lower-margin cigarettes toward higher-margin OTP, while aggregate nicotine gross profit is growing.
"That is good news because gross profit is growing for nicotine in aggregate," Rapanick said.
Changes are also visible in product merchandising. Rapanick said suppliers have responded to changes in the sales mix, and merchandising space for nicotine alternatives, including vapor products, has grown considerably over the past year.
Backbar competition is also on the agenda at this year's NACS Show. A session titled "The Battle for Back Bar Space" will focus on how retailers allocate limited space among oral nicotine, traditional tobacco and emerging categories, including considerations around merchandising and profitability.
Rapanick said he expects more brands, flavors and product innovation in the category to be on display at this year's show.
NACS Presses for Enforcement and Regulatory Clarity
Rapanick said NACS sees illicit and unregulated products as putting responsible convenience retailers at a competitive disadvantage. He also described the FDA's authorization pathway as difficult and insufficiently transparent from the retailer perspective.
NACS has made enforcement and regulatory clarity a major advocacy priority, he said, including through its involvement in the Regulate Smarter Coalition formed in 2025.
FDA has also changed parts of its approach this year. In May, the agency issued enforcement guidance covering certain unauthorized electronic nicotine delivery systems and oral nicotine pouch products.
On Sept. 28, FDA said it intends to evaluate changes to the Premarket Tobacco Product Application, or PMTA, regulatory framework, including through new rulemaking to replace the current framework. The agency said it will continue processing PMTA submissions and issuing decisions under existing statutory requirements while any changes are considered.
2027: Rapanick Expects Similar Trends
Rapanick does not expect a sharp change in direction next year.
"I would expect more of the same," he said.
He said cigarette sales have followed a broadly similar trend since the effects of the COVID period subsided, while OTP sales growth has also followed a relatively consistent pattern.
Within OTP, traditional smokeless tobacco, cigars and vapor are not performing as strongly as the Smokeless Tobacco Alternatives subcategory, Rapanick said.
Rapanick also sees considerable room for new entrants and innovative products in the U.S. market. In the short term, he said, market saturation is not yet a major concern.
2Firsts will continue to follow developments in the U.S. tobacco and nicotine market.
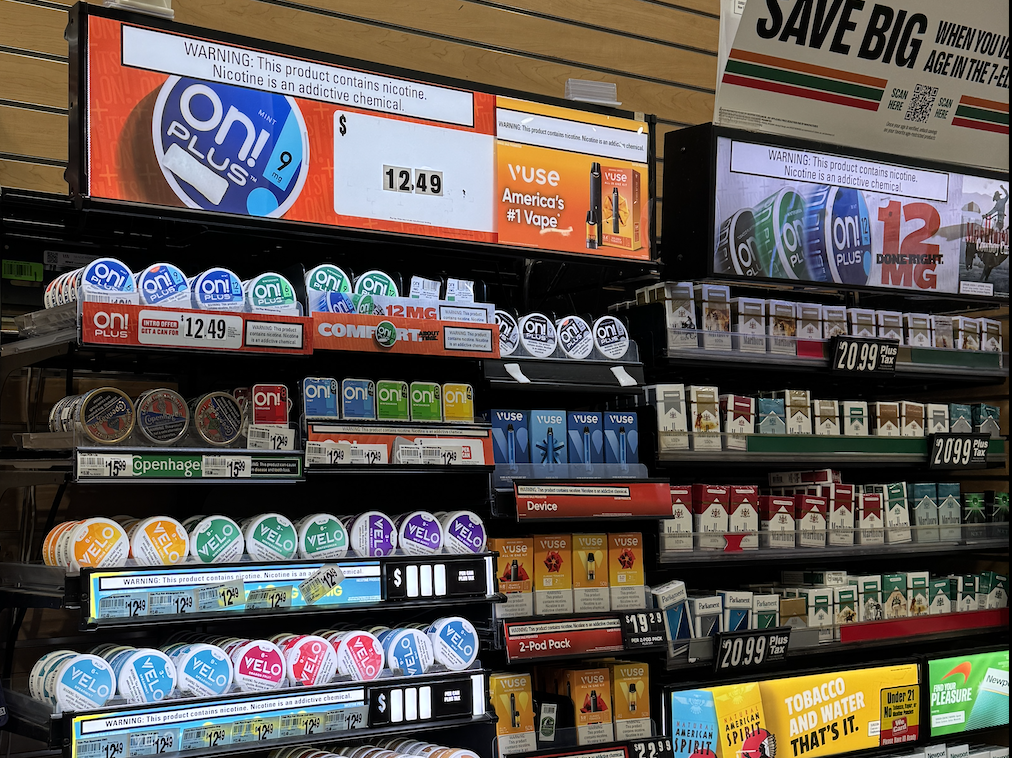
Cover image: Tobacco and nicotine products displayed at a convenience store near Times Square in New York City.| Photo: 2Firsts