Key Points
- EU finance ministers are scheduled to examine two tobacco excise directives on November 9, seeking a Council general approach.
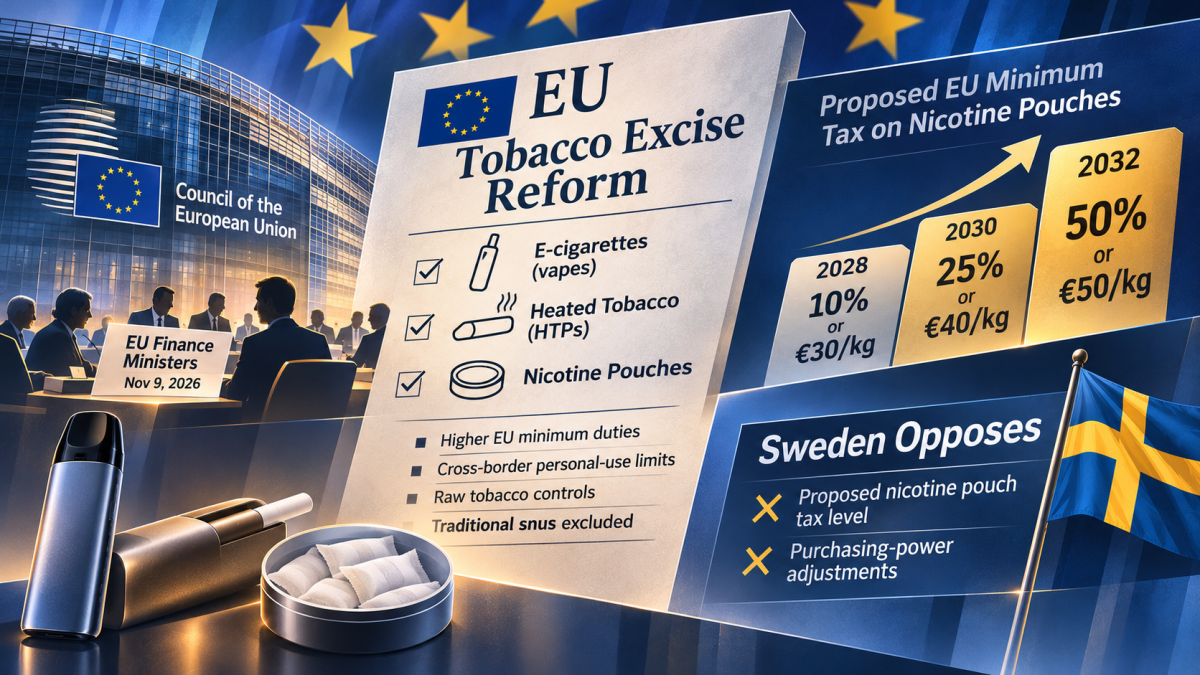
- The Irish presidency proposes phased minimum nicotine pouch duties: 10% or €30/kg in 2028, 25% or €40/kg in 2030, and 50% or €50/kg in 2032.
- Sweden says it cannot support the current compromise, opposing the nicotine pouch minimum tax level and the principle of purchasing-power adjustments.
- The reform would extend common EU minimum excise rules to e-liquids, heated tobacco and nicotine pouches, while traditional tobacco snus would remain outside the relevant directives' scope.
- The compromise also proposes halving existing reference quantities for tobacco products carried across borders for personal use and introducing reference quantities for new categories. The European Parliament previously rejected the rates directive, but the legislative process remains ongoing.
2Firsts
November 10, 2026
Finance ministers from the European Union's 27 member states are scheduled to seek a common position on tobacco excise reform at the Economic and Financial Affairs Council (ECOFIN) meeting in Brussels on November 9. The proposed overhaul would raise minimum duties on conventional tobacco and extend common EU minimum tax rules to e-cigarette liquids, heated tobacco and nicotine pouches. Nicotine pouch taxation remains a major point of disagreement, with Sweden formally stating that it cannot support the current compromise.
A Council note dated November 5, identified as ST 15387/26, states that the Irish Council presidency has revised compromise texts for two tobacco excise directives but that ministers must resolve the proposed nicotine pouch minimum rates. Under the package, the minimum duty would rise in stages beginning in 2028 and reach 50% of retail selling price or €50 per kilogram in 2032.
Nicotine Pouch Rates Remain Central Dispute as Sweden Rejects Current Compromise
The ministerial discussion concerns two related EU legislative proposals.
The first would recast the Tobacco Taxation Directive (TTD), covering the classification, structure and minimum rates of excise duty on tobacco and related products.
The second would amend Directive (EU) 2020/262 on the general arrangements for excise duties, including the administration and cross-border movement of relevant products.
The Irish presidency's November 5 compromise proposes the following phased minimum nicotine pouch duties:
| Proposed implementation date | Minimum nicotine pouch excise |
|---|---|
| January 1, 2028 | 10% of retail selling price or €30 per kilogram |
| January 1, 2030 | 25% of retail selling price or €40 per kilogram |
| January 1, 2032 | 50% of retail selling price or €50 per kilogram |
These figures are proposed EU minimum standards. Their calculation and application depend on the final legal text, while member states may set higher domestic rates.
An annotated ECOFIN agenda published by Sweden's Ministry of Finance on November 2 shows that the Swedish government cannot support the current general approach for two main reasons.
First, Sweden considers the proposed minimum excise duty on nicotine pouches substantially higher than its current domestic rate, even after reductions from the European Commission's original proposal.
The Swedish government says nicotine pouches should not face minimum tax burdens comparable to certain smoking-tobacco categories. It argues that member states should remain free to differentiate taxation according to the relative health risks of different products.
Second, Sweden opposes the principle of adjusting EU minimum excise duties according to individual member states' purchasing power.
Sweden nevertheless supports greater harmonization of definitions and administrative procedures for tobacco and nicotine product taxation, seeking to reduce compliance burdens and tax fraud. Its objections concern the current compromise rather than the entire principle of EU tax coordination.
The Council's November 5 note identifies nicotine pouch minimum rates as an issue that must be resolved by finance ministers to enable agreement on the wider package.
E-Liquids and Heated Tobacco Would Enter Common Framework With Purchasing-Power Adjustments
The European Commission proposed the overhaul on July 16, 2025, seeking to modernize the EU's tobacco excise rules and extend their coverage to newer tobacco and nicotine products.
Current EU legislation sets common minimum excise requirements for cigarettes, cigars and several other tobacco categories. However, national excise arrangements for e-liquids, heated tobacco and nicotine pouches vary across member states.
The revised framework would cover:
E-cigarette liquids, including nicotine-containing and nicotine-free liquids within the directive's scope;
Heated tobacco products;
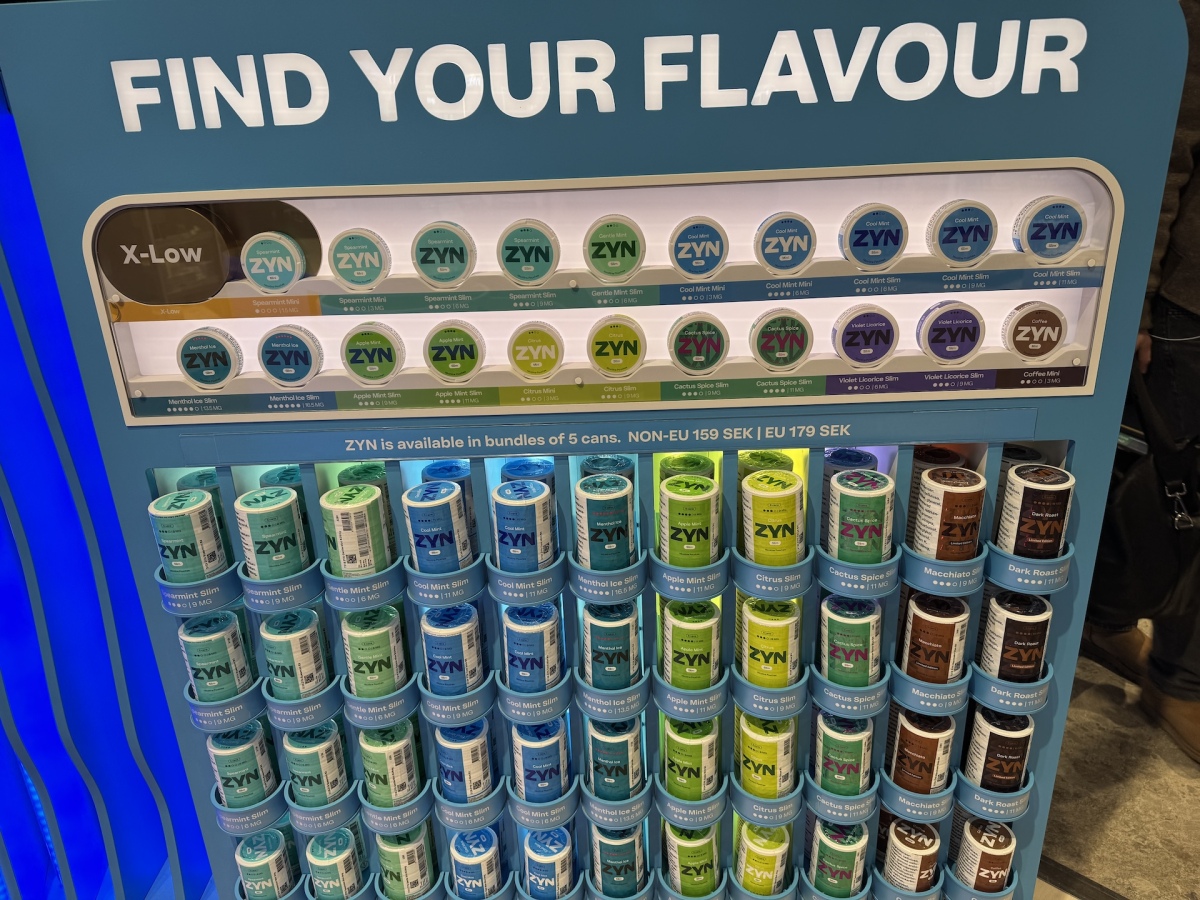
Nicotine pouches and other qualifying nicotine products;
Raw tobacco and other newly regulated categories;
Conventional cigarettes, cigars, fine-cut tobacco and other tobacco products already subject to EU minimum duties.
According to the Swedish government's description of the latest compromise, minimum excise amounts would be partly adjusted for differences in national purchasing power. As a result, the applicable minimum amounts could vary between member states.
The proposal also provides an alternative mechanism under which countries could apply tax rates 3% above the directive's minimum levels rather than use the purchasing-power adjustment.
Minimum rates would also be subject to periodic indexation on a three-year cycle, with the relevant decisions requiring unanimity in the Council.
A common EU minimum framework would change how different member states set tax floors for newer nicotine products. Actual tax burdens would still depend on the adopted directive, product definitions, national legislation and any applicable adjustment mechanism.
Traditional Swedish tobacco snus and modern tobacco-free nicotine pouches would remain separate product categories.
According to the Swedish government's account of the compromise, traditional tobacco snus would remain excluded from the relevant EU tobacco excise directives, while nicotine pouches would be brought within the common minimum tax framework.
Heated tobacco and waterpipe tobacco would also receive separate tax classifications.
The Commission has also proposed stronger oversight of raw tobacco movements to address illicit manufacturing and cross-border trade. The current package includes provisions addressing raw tobacco within the EU excise administration framework.
Cross-Border Personal-Use References Would Be Halved as Unanimity Remains Necessary
The latest compromise also includes changes to cross-border personal-use rules.
Sweden's November 2 annotated agenda states that the proposed amendments to the EU's general excise arrangements would halve the existing indicative quantities used to assess whether tobacco products transported between member states are intended for personal consumption.
The proposal would introduce corresponding reference quantities for newly covered tobacco and nicotine product categories.
These indicative quantities are used by tax authorities when assessing the purpose of cross-border movements. They are not automatic absolute limits on the amount an individual may carry.
The proposal would also allow member states that have prohibited certain product categories domestically to apply specified tax treatment when travelers bring such products across borders.
Traditional tobacco snus would remain outside the scope of the proposed amendments to the general excise arrangements.
The reform is proceeding under the special legislative procedure established by Article 113 of the Treaty on the Functioning of the European Union.
On June 17, 2026, the European Parliament issued its consultative opinions on both proposed directives. It rejected the directive on tobacco excise structures and rates, while proposing amendments to the directive on general excise arrangements.
Parliament's position forms part of the consultation procedure. The Council retains responsibility for the legislative decision under the applicable rules, and unanimity among member states is required.
The Council's November 5 note states that member-state representatives examined the presidency's compromise on October 28. Several delegations supported efforts to reach an agreement, although reservations about the overall package remained.
The Irish presidency subsequently revised the texts and referred the unresolved nicotine pouch minimum rates to the November 9 ministerial meeting.
If ministers reach a general approach, the revised texts would still have to proceed through the applicable legislative process, including further consultation with the European Parliament. A general approach would not itself make the proposed tax rates legally binding.
At the time of reporting, the Council had not announced a final agreement on the tobacco taxation package at its November 9 meeting. Whether the nicotine pouch rates and purchasing-power provisions secure unanimous support remains subject to ministerial negotiations.
Follow 2Firsts for updates on EU and global tobacco and nicotine taxation, regulatory developments and industry trends.
Cover Image generated by AI