Key Points
● Capital Repricing: As heated tobacco, vaping and nicotine pouches scale up, investors are looking beyond cigarette-volume declines to assess the long-term earnings and cash-flow potential of the broader nicotine portfolio.
● Profitability Remains Central: The key question is whether newer nicotine categories can replace cigarette sales while preserving or improving margins.
● Regulation Shapes Startup Value: In highly regulated industries, regulation is not a secondary issue but a core part of the business model, growth outlook and valuation.
● Engagement vs. Divestment: Hexis argues that active ownership, voting and board engagement may influence corporate transition more directly than simply exiting tobacco investments.
● A Broader Financial Shift: The transition is extending beyond company valuations into taxation, insurance pricing and wider capital-allocation decisions.
2Firsts
NEW YORK, Oct. 5, 2026
The expansion of heated tobacco, e-cigarettes and nicotine pouches is changing the investment case for the global tobacco and nicotine industry, analysts and fund managers told a New York conference.
The New Approaches Summit on Sept. 25 devoted a separate session to capital, alongside its discussions of science, regulation and innovation. Its chair, Huub Savelkouls, said the financial and fiscal consequences of the industry’s transition had received less attention than product science.
For a trillion-dollar industry, those questions extend beyond share prices. They concern the funding of new products, the durability of earnings and the ability of shareholders to influence the pace of change.
2Firsts attended and reported on the full capital session, including its four presentations and subsequent panel discussion. Savelkouls chaired the session and gave its opening presentation. Bradley Tusk, Andrei Andon-Ionita and Pieter Vorster also spoke, with Joel Rubenstein joining the panel.
Their discussions covered two distinct markets for capital: established tobacco companies financing new businesses alongside cigarettes, and startups whose prospects depend on navigating regulatory barriers.

Reassessing demand and profitability
Andon-Ionita, Jefferies’ global tobacco equity research analyst, said investor interest in the sector had increased over the past few years as newer nicotine categories reached greater scale.
He argued that cigarette declines were becoming a less useful guide to the industry’s long-term prospects as consumers moved into other nicotine products. Investors were increasingly treating that shift as a change in the business model rather than a temporary product trend.
A chart in his presentation, citing Jefferies and Euromonitor, put next-generation products at 23% of global nicotine volumes in 2024. The breakdown was 18% for e-vapour, 4% for heated tobacco and 1% for oral nicotine pouches. Combustibles accounted for 75%, with traditional oral tobacco making up the remaining 2%.
Profitability was central to his argument: newer categories needed to generate earnings as well as replace cigarette sales.
His presentation used Philip Morris International to illustrate that point. A chart citing company data and Jefferies estimates put PMI’s group earnings before interest and tax margin at 41.2% in 2015 and 42.0% in 2025. Jefferies projected a margin of 47.4% in 2030.
Andon-Ionita said PMI had expanded its newer businesses while preserving overall profitability, giving investors a reason to reconsider how long the company could sustain its earnings.
He also pointed to capital expenditure, arguing that the large tobacco companies he covered had kept fixed-asset spending modest relative to sales while expanding newer categories. In his view, that allowed investment and cash returns to shareholders to continue alongside each other.
A separate Jefferies and FactSet chart showed PMI at roughly 360 on a total-shareholder-return index starting at 100 in September 2016 and running through September 2026. His comparison of consumer-sector dividend yields, which included forecasts through 2027, also placed tobacco above the other sectors shown.
Those figures supported his view that product transition, profitability and cash returns could coexist within large tobacco companies.
Cash flow, taxes and insurance
Savelkouls, an independent business strategy and public-policy consultant and former PMI chief sustainability officer, examined how the transition interacts with the wider financial system.
He emphasized established tobacco companies’ cash generation as a source of funding for newer products. His presentation compared share issuance, buybacks and dividends, and he questioned how much divestment could influence mature businesses with limited reliance on fresh equity funding.
He also argued that capital markets were recognizing progress toward modern nicotine through higher price-to-earnings valuations and lower debt costs.
His fiscal questions were different. Taxes intended to change behavior also provide government revenue. He asked how governments would replace that income if the taxed activities declined as intended, illustrating the issue with a comparison of alcohol, tobacco and mineral-oil excise receipts against defense spending in selected countries.
Insurance presented another pricing question. Savelkouls reproduced Swiss Re material distinguishing risk groups among smokers and users of alternative products. The accompanying statement said pricing frameworks had yet to systematically incorporate an intermediate-risk group between smokers and never-smokers.
He argued that more differentiated insurance pricing could offer consumers a financial incentive to switch. It was one of several ways in which he expected the transition to reach beyond manufacturers’ balance sheets.
Exclusion or shareholder engagement
Vorster, chief executive of Hexis Capital Management, challenged the use of sector-wide tobacco exclusions by institutional investors.
His presentation cited a Wilshire estimate putting the cumulative present-value cost of CalPERS’ tobacco divestment since 2001 at $6.16 billion as of June 30, 2025. It also put assets represented by signatories to the Tobacco-Free Finance Pledge at more than $19 trillion.
Vorster argued that selling shares transferred ownership and voting rights without necessarily changing the underlying business. He favored remaining a shareholder and pressing companies for specific changes.
The companies themselves had changed since many exclusion policies were adopted, he said. His presentation showed PMI’s smoke-free share of net revenue rising from 2.7% in 2016 to 41.5% in 2025.
Hexis has put that approach into an investment product. The Hexis Active Nicotine Engagement ETF, trading as NICO, launched on May 6, 2026 and is listed on NYSE Arca, according to the presentation.
The actively managed fund combines investment in listed tobacco and nicotine businesses with a shareholder-engagement program. Its proprietary Hexis Nicotine Transition Score, or HNTS, assesses companies’ current position and potential growth in products Hexis classifies as reduced-risk, alongside governance and related factors.
The framework assigns 40% of the score to the current reduced-risk position, 35% to growth potential and 25% to governance, engagement and sustainability. It uses 27 indicators and 13 sub-indicators.
The score feeds into a discounted cash-flow valuation model. Position sizes depend on the difference between Hexis’ valuation and the market price; a high transition score does not automatically trigger a purchase.
A company further along in its transition may already command a higher valuation, while a lower-scoring business could offer an opportunity at a sufficient discount, the presentation said.
The same framework guides requests to company boards. Hexis seeks board oversight of harm-reduction commitments and capital allocation aligned with them. More specific requests can concern research spending, executive pay, responsible marketing, prevention of youth access and disclosure.
Vorster said Hexis votes its shares and engages directly with companies. Asked during the panel about their response, he said it had been more positive than he expected. He also described differing levels of support within companies for the pace of transition.
His case for engagement rests on investors being able to turn an ownership position into pressure for measurable action. The fund had been operating since May, and his presentation described its methodology and early engagement activity.
Regulation in the venture-capital calculation
Tusk, founder and CEO of Tusk Ventures, approached the sector through his experience investing in highly regulated industries rather than as a tobacco specialist.
He said his investment process considered founders and technology alongside regulatory obstacles or opportunities that could affect growth and valuation.
Recalling his work as Uber’s first political adviser, Tusk described how the company drew on customer support in disputes over its ability to operate. He said media, public communication and consumer participation had become important alongside conventional lobbying.
His focus was on the gap between demand for a product and permission to build a business around it. For the startups he discussed, navigating regulation was part of developing the commercial opportunity, not a task to leave until after investment.
Different products, different markets
During the panel, Savelkouls asked whether one modern nicotine category would eventually dominate.
Andon-Ionita expected a more varied market than the one built around cigarettes. He pointed to heated tobacco in Japan and parts of Central and Eastern Europe, vaping in the United States and United Kingdom, and nicotine pouches in Sweden and the United States.
Consumer habits and regional differences would continue to matter, he said. He also suggested that investors’ expectations for nicotine pouches were concentrated in markets where the category had already shown traction. Success elsewhere could provide growth beyond those assumptions.
Rubenstein, a consultant to the Global Institute for Novel Nicotine with smoking-cessation business experience at GSK, BAT and PMI, offered a different perspective on nicotine replacement therapy, or NRT.
Asked about its future, he described NRT primarily as a fallback for tobacco companies in markets where non-pharmaceutical nicotine products face restrictions. In his view, that role was different from being a primary growth business.
Questions from the audience also raised illicit trade. Responding to one on taxation and illegal markets, Vorster described illicit trade as a significant issue and pointed to Australia in discussing sharp tax increases. He treated the issue as a risk to the outlook for the regulated industry.
What investors believe
Vorster also questioned whether financial professionals had the information needed to assess the transition.
His final slide reported an informal poll conducted during a Hexis webcast for U.S. financial professionals on Sept. 1. Asked about the health risk of using e-cigarettes compared with smoking cigarettes, 51% of respondents selected “about the same, or higher.” Hexis described the poll as indicative, not a scientific sample.
Vorster used the result to argue that investor education should accompany financial analysis and shareholder engagement. The subject also provided the framing for the panel, titled “Navigating Misinformation: Capital, Consumers, & Market Realities.”
The approaches presented in New York give capital several roles in the industry’s next phase: assessing the earnings of newer products, financing businesses with viable regulatory paths and pressing companies to account for their investment decisions.
For Hexis, that last role already extends to board oversight, research budgets, executive incentives and disclosure. These are concrete channels through which shareholders seek to influence the transition, alongside the prices they are prepared to pay for companies’ shares.
Capital’s contribution will depend on both the businesses it finances and the changes its owners can secure. As companies build the next generation of tobacco and nicotine businesses, investment decisions can shape not only their scale and direction, but also the standards of transparency and governance under which they operate.
For continuing coverage of global tobacco and nicotine capital markets, follow 2Firsts. To contribute an article or share your perspective in an interview, contact alan@2firsts.com.
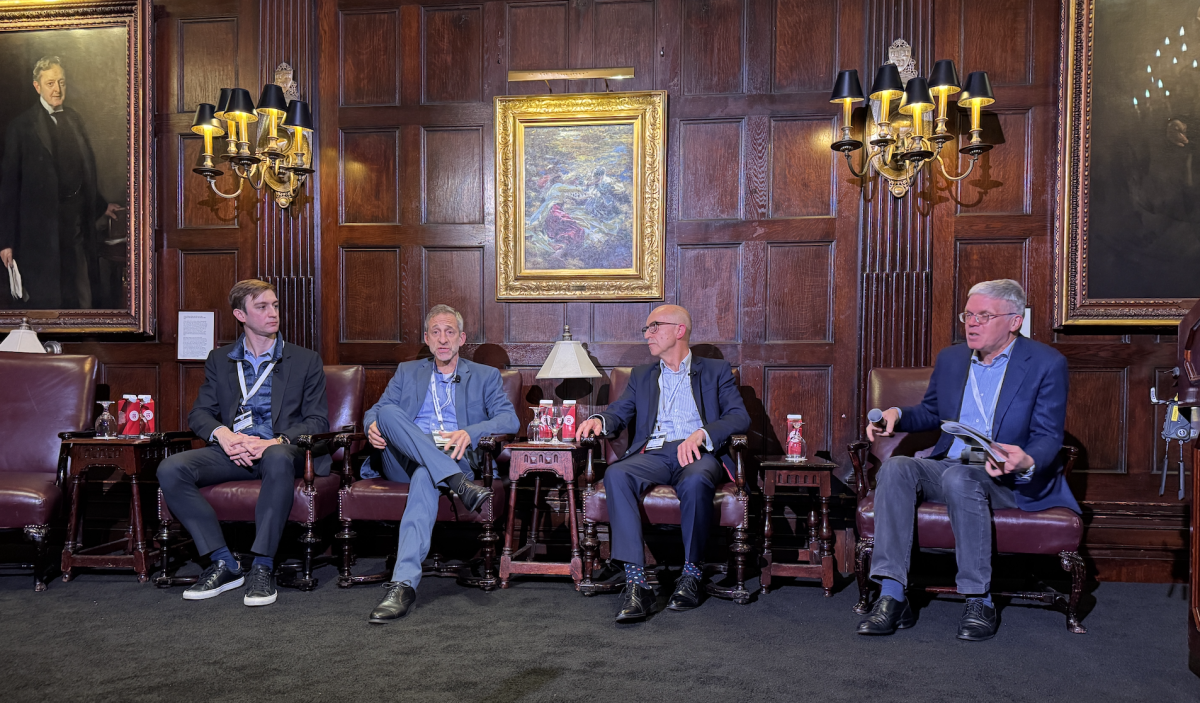
Cover image: The capital and modern nicotine panel at the 2026 New Approaches Summit. From left: Andrei Andon-Ionita, Joel Rubenstein, Pieter Vorster and Huub Savelkouls. | Photo: 2Firsts
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.