Key Points
- In September 2026, the Texas Comptroller issued private letter ruling 202609004L, classifying a combustible product containing 6-MN and non-tobacco plant material as a taxable tobacco product rather than a cigarette.
- The ruling applies the Texas Supreme Court's May 8 decision involving VELO nicotine pouches, examining whether a product's primary ingredients replace the material and functions of tobacco in traditionally taxed products.
- The Supreme Court held that the VELO pouches at issue were taxable but remanded RJR Vapor's unresolved equal-and-uniform taxation challenge to a lower appellate court.
- The private letter ruling concerns specific taxpayer facts and is not a generally applicable judicial precedent. Texas law expressly excludes qualifying e-cigarettes from the relevant tobacco-products tax definition.
2Firsts
November 6, 2026
The Texas Comptroller of Public Accounts ruled in September 2026 that a combustible product made with non-tobacco plant material and 6-methylnicotine (6-MN), a synthetic nicotine analog, qualifies as a taxable tobacco product, even though the applicant said it contained no tobacco leaf or measurable conventional nicotine.
The agency confirmed the determination, identified as private letter ruling 202609004L, in its October tax policy bulletin. U.S. law firm Troutman Pepper Locke said in a November 5 analysis that the decision applies reasoning from an earlier Texas Supreme Court ruling involving VELO nicotine pouches to a combustible product containing a synthetic nicotine analog.
Texas Classifies a Combustible 6-MN Product as Taxable Tobacco
The product covered by the ruling is described as an ersatz cigarette, or ercig, marketed as a combustible alternative to conventional cigarettes.
According to the taxpayer's submission, the product contains U.S.-grown non-tobacco plant biomass and 6-MN, a synthetic nicotine analog, but no conventional nicotine.
The taxpayer described 6-MN as a nicotinic acetylcholine receptor agonist with pharmacological activity comparable to nicotine. That description was supplied by the applicant and was not an independent scientific assessment of the compound's effects or safety by the tax authority.
The manufacturer asked whether its product qualified as a cigarette or another tobacco product under Texas tax law.
The Comptroller determined that the product did not meet the definition of a cigarette under Section 154.001(2) of the Texas Tax Code because it did not contain tobacco. It also did not qualify as a cigar under Chapter 155.
However, Section 155.001(15)(E) includes certain products made from tobacco or a tobacco substitute within the state's tobacco-products tax.
The Comptroller found that the product's plant material served functions comparable to conventional smoking tobacco in structure, aroma, flavor and combustion.
Based on the taxpayer's description of 6-MN, the Comptroller also treated the compound as performing a role comparable to that of nicotine.
The agency concluded that the plant material and 6-MN together constituted a functional substitute for tobacco. The product was therefore subject to the applicable tobacco-products tax, licensing and reporting requirements.
Texas imposes a weight-based tax on relevant tobacco products other than cigars. The ruling established the product's tax classification, but the publicly available summary did not specify its taxable weight or the resulting tax liability.
VELO Ruling Provides Legal Basis; Constitutional Tax Challenge Remains
The determination draws on the Texas Supreme Court's May 8, 2026, ruling in Hancock v. RJR Vapor Co., LLC.
The case concerned VELO nicotine pouches sold by R.J. Reynolds Vapor Company, a subsidiary of British American Tobacco (BAT).
VELO pouches use non-tobacco plant material, including microcrystalline cellulose, together with tobacco-derived nicotine. They do not contain the pulverized tobacco leaf used in traditional oral tobacco products.
RJR Vapor challenged the Texas tobacco-products tax after paying under protest and filing a refund lawsuit, arguing that VELO pouches were not taxable tobacco products under state law.
The Texas Supreme Court concluded that the primary ingredients of VELO pouches — a mixture of non-tobacco plant matter and nicotine — replaced the tobacco material used in traditional oral tobacco products such as moist snuff and snus.
The court held that the statutory definition of a tobacco substitute required examining whether a product's primary ingredients or components performed the role of tobacco plant matter in products expressly subject to the tax.
The court also held that nicotine alone did not constitute a tobacco substitute. It left open whether plant matter without nicotine could satisfy the statutory definition.
The Supreme Court reversed the lower appellate court's ruling that VELO pouches were not taxable and held that the products qualified as taxable tobacco products.
However, the case's constitutional issues were not fully resolved.
RJR Vapor argued that taxing VELO pouches while treating certain nicotine replacement therapies differently could violate the Texas Constitution's requirement that taxation be equal and uniform.
The Supreme Court did not resolve that equal-and-uniform challenge and remanded it to the court of appeals for further consideration.
The Texas Comptroller's public guidance now classifies all oral nicotine pouches as Class W taxable tobacco products. That classification does not automatically establish the tax treatment of every product containing a nicotine analog.
6-MN Interpretation Remains Untested in Court; E-Cigarettes Excluded
The September private letter ruling extends the functional-substitution reasoning applied to VELO nicotine pouches to a combustible product that contains no conventional nicotine.
In its November 5 analysis, Troutman Pepper Locke identified two extensions of the Supreme Court's reasoning: from oral pouches to combustible products, and from products containing nicotine to those containing a synthetic nicotine analog.
The law firm noted that the Supreme Court had expressly rejected the argument that nicotine alone constituted a tobacco substitute and had declined to decide whether plant matter without nicotine would meet the statutory definition.
In the September determination, the Comptroller relied on the taxpayer's description of 6-MN's pharmacological activity to conclude that the compound, combined with non-tobacco plant material, performed the functions of tobacco in a conventional smoking product.
No court has ruled on that specific interpretation.
A private letter ruling is a written determination addressing the application of tax law to the particular facts submitted by a taxpayer. Subject to the relevant factual and procedural conditions, it binds the Comptroller and may be relied upon by the requesting taxpayer. It is not a generally applicable judicial precedent.
The September ruling does not establish that all products containing 6-MN qualify as taxable tobacco products.
Section 155.001(15)(E) of the Texas Tax Code expressly excludes e-cigarettes meeting the applicable statutory definition. The private letter ruling does not extend its tobacco-products tax classification to 6-MN vaping products.
The state tax classification also does not constitute marketing authorization from the U.S. Food and Drug Administration (FDA).
Troutman Pepper Locke noted that statutes in other states, including Alaska and Oklahoma, contain language concerning tobacco substitutes. Whether similar products would receive the same tax treatment depends on the laws and regulatory interpretations in each jurisdiction.
Follow 2Firsts for timely updates on global tobacco and nicotine regulations, market developments and industry trends.
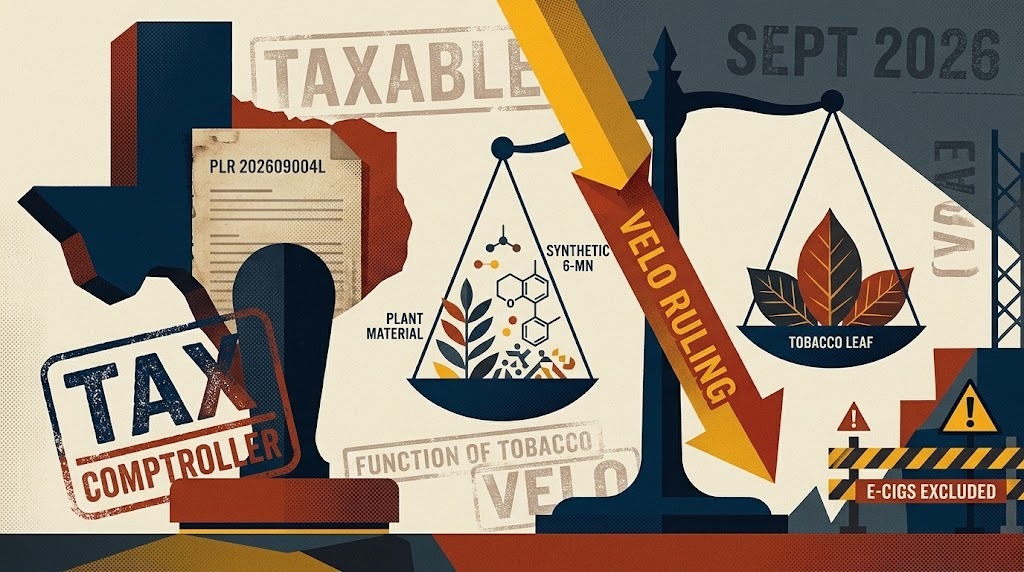
Cover Image generated by AI
References:
- Texas Comptroller — October 2026 Tax Counsel News
- Texas Comptroller — Private Letter Ruling 202609004L
- Supreme Court of Texas — Hancock v. RJR Vapor Co., May 8, 2026
- Troutman Pepper Locke — Texas Comptroller Rules Synthetic-Nicotine-Analogs Are Taxable Tobacco Products
- Texas Comptroller — Tobacco Products Tax FAQ
- Texas Tax Code — Chapter 155
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.