Key Points
- Germany's Bundestag approved tobacco tax amendments on October 15, 2026, providing for annual increases from 2027 through 2030 across vaping, heated tobacco and conventional tobacco products.
- Excise duty on qualifying e-liquids and tobacco substitutes will rise from €0.32/ml in 2026 to €0.38/ml in 2027 and €0.44/ml in 2030, a cumulative increase of 37.5%.
- Heated tobacco will retain its tax calculation based on 80% of the corresponding cigarette excise duty, with its tax burden increasing as cigarette duties rise.
- Average retail prices for a pack of 20 cigarettes are projected to approach €12 by 2030, with some brands potentially reaching €14.
- The revised bill is projected to generate €11.824 billion in additional tax revenue from 2027 to 2030, while tobacco industry representatives warn of potential growth in illicit trade.
2Firsts
October 16, 2026
Germany's Bundestag passed amendments to the Tobacco Tax Act on October 15, setting out annual excise tax increases from 2027 through 2030 covering e-cigarette liquids, heated tobacco, cigarettes and other tobacco products. Under the Finance Committee's amended bill, duty on qualifying e-liquids will rise from €0.32 per milliliter in 2026 to €0.44 in 2030, an increase of 37.5%. Heated tobacco will retain a tax calculation based on 80% of the corresponding cigarette excise duty, while the average retail price of a 20-cigarette pack is projected to approach €12 by 2030. The revised measure is expected to generate approximately €11.8 billion in additional tax revenue over four years.
The amendments were approved in the version submitted by the Bundestag's Finance Committee on October 14 under document 21/8605.
The governing Christian Democratic Union/Christian Social Union (CDU/CSU) and Social Democratic Party (SPD) supported the bill. Alternative for Germany (AfD), the Greens and the Left voted against it, along with two lawmakers from the CDU/CSU parliamentary group.
The Finance Committee raised several proposed tax rates compared with the government's original bill and revised implementation dates and tax stamp arrangements for certain product categories.
E-Liquid Duty to Reach €0.44/ml by 2030, Up 37.5% From 2026
The reform increases Germany's existing excise duty on products classified as tobacco substitutes (Substitute für Tabakwaren), including substances intended for use in electronic cigarettes.
Germany already levies a volume-based excise tax on e-liquids. The applicable rate in 2026 is €0.32 per milliliter.
Under the Bundestag-approved version, the rate will increase annually from 2027 through 2030.
| Year | Original Government Proposal | Bundestag-Approved Version | Change From 2026 |
|---|---|---|---|
| 2026 | €0.32/ml | €0.32/ml | — |
| 2027 | €0.33/ml | €0.38/ml | +18.75% |
| 2028 | €0.34/ml | €0.40/ml | +25.00% |
| 2029 | €0.35/ml | €0.42/ml | +31.25% |
| 2030 | €0.36/ml | €0.44/ml | +37.50% |
The Finance Committee raised the proposed 2027 rate from €0.33 to €0.38 per milliliter and the 2030 rate from €0.36 to €0.44 per milliliter.
For a 10 ml bottle of e-liquid subject to the duty, the excise tax would increase from €3.20 in 2026 to €3.80 in 2027 and €4.40 in 2030.
That represents an additional €1.20 in excise duty per 10 ml by 2030, excluding VAT and other retail costs.
In its amended bill, the Finance Committee assumed that the additional excise tax costs would be passed on to consumers through higher product prices.
The tobacco-substitute classification is defined under German tax law and covers qualifying substances used in e-cigarettes. The per-milliliter rate does not automatically apply to all alternative nicotine products, including nicotine pouches.
Heated Tobacco Retains Tax Formula Based on 80% of Cigarette Duty
Heated tobacco products (HTPs) are also covered by the scheduled tax increases.
Under Germany's Tobacco Tax Act, heated tobacco is taxed through a combination of pipe tobacco duty and an additional excise component.
The additional component is calculated as 80% of the corresponding cigarette excise duty minus the pipe tobacco duty. The total tax liability is determined under the statutory formula.
For the calculation, each individually portioned heated tobacco stick is treated as equivalent to one cigarette.
The Finance Committee retained this mechanism in its amended bill.
As cigarette excise duties rise from 2027 through 2030, the corresponding tax liability on heated tobacco will also increase.
Under the government's original proposal, the Federal Ministry of Finance estimated that the average excise tax on heated tobacco would rise from 16.65 euro cents per stick in 2026 to 23.12 euro cents by 2030.
The Finance Committee subsequently raised cigarette tax rates. The 23.12-cent estimate therefore reflects the original government proposal rather than a recalculated amount under the Bundestag-approved amendments.
Cigarette Pack Prices Seen Near €12 by 2030, With Some Brands Potentially Reaching €14
The amendments also provide for annual increases in conventional cigarette excise duties from 2027 through 2030.
Germany's cigarette excise tax combines a fixed duty per cigarette, a percentage of the retail price and minimum duty requirements.
The Finance Committee raised the ad valorem component to 21.05% and increased the fixed duty for each year.
| Year | Fixed Excise Duty per Cigarette | Ad Valorem Rate |
|---|---|---|
| 2027 | 14.34 euro cents | 21.05% |
| 2028 | 15.63 euro cents | 21.05% |
| 2029 | 17.04 euro cents | 21.05% |
| 2030 | 18.57 euro cents | 21.05% |
The figures are taken from the Bundestag-approved amendments. Actual excise liability is also subject to statutory minimum duty requirements.
According to German public broadcaster Tagesschau, the weighted average retail price of a pack of 20 cigarettes is projected to increase from approximately €8 currently to almost €12 by 2030.
Some cigarette brands could reach €14 per pack.
These are price forecasts based on the proposed tax changes and expected retail market developments, rather than legally mandated selling prices.
The Finance Committee's fiscal estimates assume that the higher excise duty costs will be fully passed on to consumers.
Fine-cut tobacco, used for hand-rolled cigarettes, is also scheduled for annual tax increases during the four-year period.
Other Tobacco Products Face Higher Duties as Tax Stamp Transition Rules Change
The legislation also covers cigars, cigarillos, pipe tobacco and waterpipe tobacco.
The Finance Committee's amended bill establishes the following implementation schedule for the main product categories:
| Product Category | First Scheduled Adjustment | Main Change |
|---|---|---|
| Cigarettes | January 1, 2027 | Higher fixed and ad valorem excise duties |
| Fine-cut tobacco | January 1, 2027 | Revised weight-based, price-based and minimum duties |
| Heated tobacco | January 1, 2027 | Higher duty linked to cigarette taxation, retaining the 80% benchmark |
| E-liquids and tobacco substitutes | January 1, 2027 | Increase from €0.32/ml to €0.38/ml |
| Cigars and cigarillos | March 1, 2027 | Certain revised rates and transitional provisions take effect |
| Pipe tobacco | March 1, 2027 | Certain revised rates and transitional provisions take effect |
| Waterpipe tobacco | March 1, 2027 | Certain revised rates and transitional provisions take effect |
The Finance Committee also revised the arrangements for tax stamps required under the new rates.
Under the amendments, new tax stamps for cigarettes, fine-cut tobacco, heated tobacco and tobacco substitutes may be obtained five weeks before the revised rates take effect, subject to the relevant requirements.
This transitional provision applies to the late-2026 switch to the new tax rates. The same accelerated arrangement is not required for cigars, cigarillos, pipe tobacco and waterpipe tobacco, whose revised rates begin in March 2027.
Germany Projects €11.8 Billion in Additional Revenue as Industry Warns of Illicit Trade
The German government has presented the tobacco tax increases as part of its federal budget consolidation efforts, while also citing public health objectives.
According to Finance Committee document 21/8605, the amended rates are projected to generate the following additional federal tax revenue:
| Fiscal Year | Estimated Additional Tax Revenue |
|---|---|
| 2027 | €1.507 billion |
| 2028 | €2.437 billion |
| 2029 | €3.419 billion |
| 2030 | €4.461 billion |
| 2027–2030 total | €11.824 billion |
Figures represent projected incremental federal tax revenue by fiscal year, not Germany's total annual tobacco excise receipts.
Finance Minister Lars Klingbeil told German public broadcaster ARD that the increases were intended to support budget consolidation and strengthen public health protection.
He referred to a federal budget shortfall of approximately €34 billion and identified the health of children and young people as a priority.
Tobacco industry representatives have questioned the government's revenue forecasts.
Industry groups warned that higher taxes on legal tobacco products could encourage consumers to turn to smuggled, illicit or untaxed products purchased abroad, potentially reducing sales through authorized retailers.
The governing coalition also acknowledged concerns about illicit trade, cross-border purchasing and untaxed imports. Lawmakers called for stronger customs enforcement and greater harmonization of tobacco taxation across the European Union.
Public health organizations, including the German Cancer Research Center (DKFZ), supported higher tobacco taxes, arguing that increased prices could help reduce smoking and discourage young people from starting.
Germany's 2025 microcensus found that approximately 19% of people aged 15 and older smoked. Tagesschau also cited DKFZ data estimating that about 131,000 people died from tobacco-related diseases in Germany in 2023.
Bundestag Approves Amendments, With Further Legislative Procedures Pending
Germany's Bundestag approved the amended Tobacco Tax Act on October 15, 2026, adopting the version submitted by the Finance Committee under document 21/8605.
The Bundesrat, Germany's upper chamber representing the federal states, had not objected to the government's original proposal.
As of October 16, however, the official records reviewed had not confirmed the completion of the Bundesrat's subsequent procedures concerning the final Bundestag-approved version.
The main tax increases for e-liquids, heated tobacco, cigarettes and fine-cut tobacco are scheduled to begin on January 1, 2027, subject to completion of the legislative process.
Certain revised rates for other tobacco products are scheduled to take effect on March 1, 2027.
Follow 2Firsts for timely updates on global tobacco and nicotine regulations, tax policy and market developments.
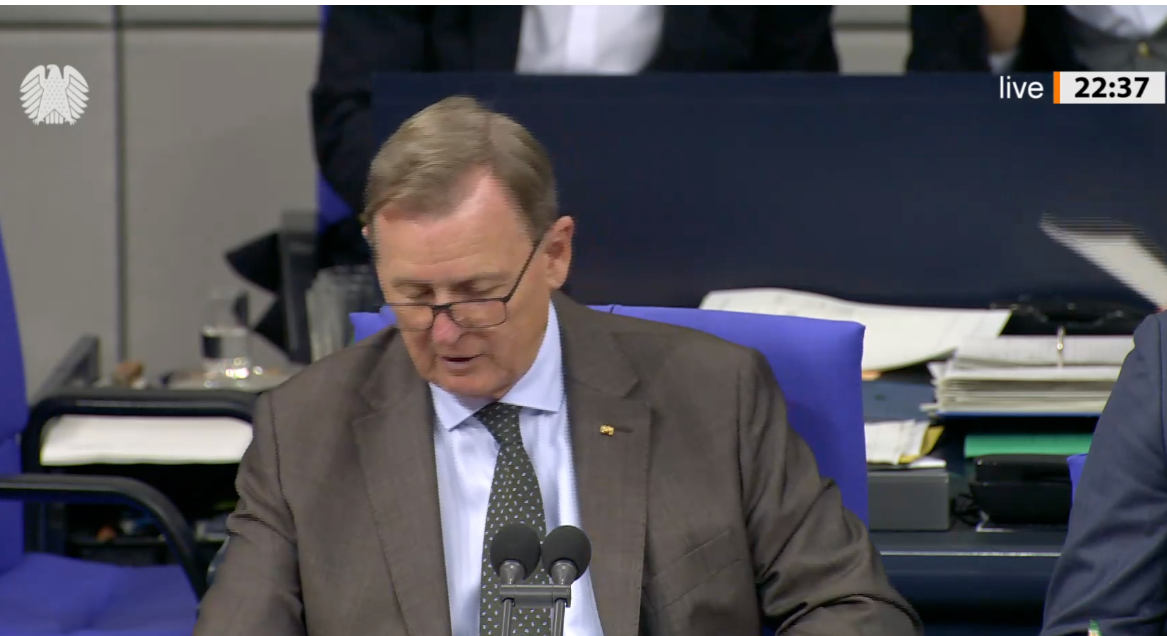
Cover Image Source: Deutscher Bundestag
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.