Cover image generated by AI.
Disclaimer: This article is intended solely for industry and academic research purposes and does not constitute investment advice.
Key Points
● Nicotine Pouch Growth: CCB International Securities' Charlie Chen forecasts annual global growth of 30–50% for nicotine pouches, outpacing vaping and heated tobacco.
● Regulation and Competition: Stronger U.S. enforcement against noncompliant vaping products could benefit legally operating companies, although consumer demand may not automatically shift to authorized alternatives.
● Company Valuations: Growth prospects, profitability and cash reserves influence tobacco company valuations. CCB International applies different valuation methods to companies including BAT, Smoore and RELX.
● Global Competition: Multinational tobacco groups benefit from established distribution networks and regulatory experience, while Chinese companies have strengths in technology, manufacturing and flexible business models.
● Investment Outlook: U.S. vaping enforcement, nicotine pouch regulation and industry consolidation are key areas to watch, alongside profitability and shareholder engagement discussed at the New Approaches Summit.
2Firsts
HONG KONG, Nov. 11, 2026 — Nicotine pouches could grow by 30% to 50% annually over the next several years, substantially outpacing vaping and heated tobacco, as regulation and smoke-free earnings become increasingly important to tobacco company valuations, according to Charlie Chen, Head of Research at CCB International Securities, the Hong Kong-based securities arm of China Construction Bank.
In written responses to 2Firsts in Chinese, Chen examined how regulatory enforcement, differences in product growth and changing business models could affect the way investors value established tobacco companies and newer nicotine businesses.
In May 2026, Chen's team published a research report titled Harm reduction: new focus of investing in the tobacco industry. The report examined growth prospects across emerging nicotine categories and the investment cases for established multinational tobacco companies and newer industry participants.
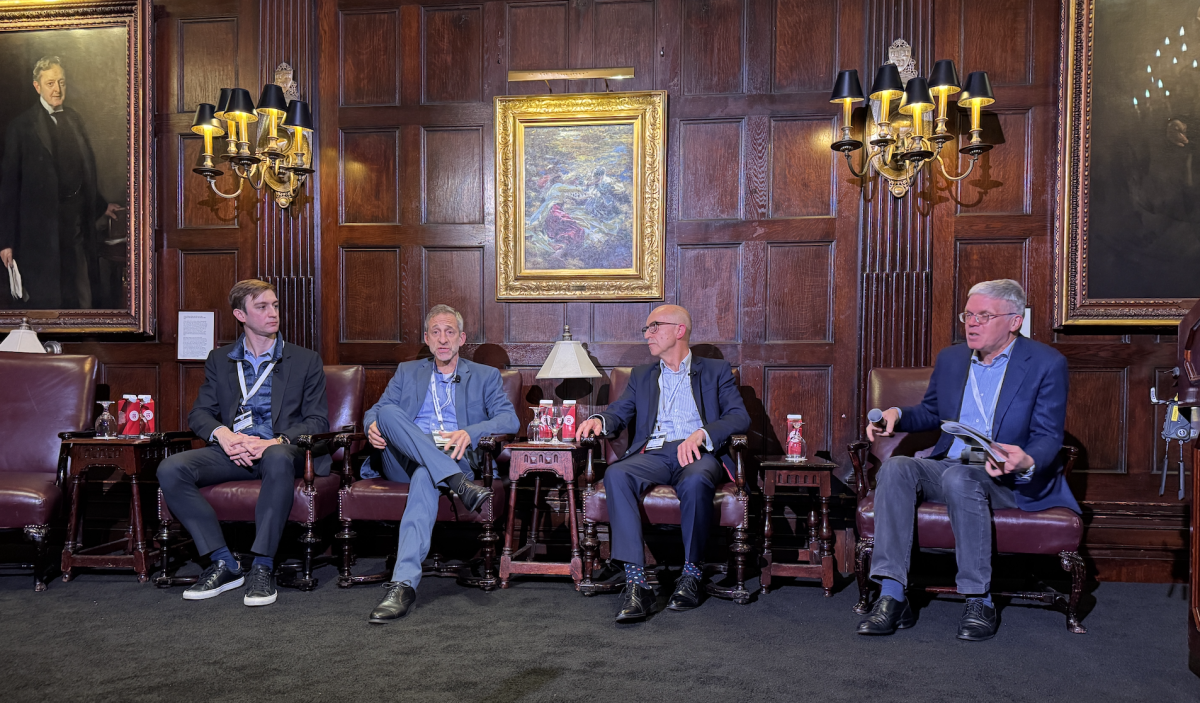
2Firsts attended the New Approaches Summit (NAS) in New Yorkon September 25. The conference included a dedicated session on capital markets, where equity analysts, asset managers and venture capital investors discussed how newer nicotine products were influencing tobacco companies' growth, profitability, valuations and capital allocation.
Andrei Andon-Ionita, Jefferies' global tobacco equity research analyst, told the conference that investor interest in the sector had increased in recent years as newer nicotine categories reached greater scale. Declining cigarette volumes alone, he argued, were becoming a less useful measure of the industry's long-term prospects.

Regulatory enforcement could reshape competition in tobacco markets
Looking back at the May report, Chen identified a shift in regulatory attitudes and enforcement, particularly in the United States, as one of the most significant developments affecting the global market for newer tobacco and nicotine products.
"There has long been a view in capital markets that without regulation, the industry descends into chaos, but with regulation, it is stifled," Chen said.
Without effective oversight, emerging tobacco and nicotine markets can experience disorderly competition. Yet when regulations are introduced without sufficient enforcement, noncompliant businesses may continue selling through unauthorized or informal channels while companies that follow the rules face tighter restrictions.
The problem has been particularly evident in the vaping market. Noncompliant products have competed through a wide selection of flavors, while lawfully operating companies have faced strict requirements covering product development, marketing and market authorization.
Chen argued that the mismatch between regulatory requirements and enforcement had left some compliant companies at a competitive disadvantage.
He is closely watching recent enforcement developments in the United States. If action against noncompliant vaping products continues, he believes it could improve competitive conditions for legally operating companies and change investors' expectations for their future growth.
That outcome, however, is not automatic.
Removing unlawful products from the market does not necessarily mean consumers will switch to existing legally marketed alternatives. Whether compliant companies can capture that demand will depend on their ability to offer products consumers want, expand production and maintain adequate distribution.
Nicotine pouches could grow 30–50% annually as category outlooks diverge
Chen expects nicotine pouches, vaping and heated tobacco to follow different growth trajectories over the next several years.
Nicotine pouches could be the fastest-growing major category, with annual global growth of 30% to 50%. By comparison, he expects both vaping and heated tobacco to expand at mid- to high-single-digit rates globally.
He cautioned that estimates of the global tobacco and nicotine market vary considerably because of illicit and noncompliant trade, as well as differences in how research organizations define and measure the market.
For that reason, he favors using estimated ranges rather than presenting a single market-size figure.
Based on his assessment of relevant companies' expected sales in 2026, Chen puts the global nicotine pouch market at approximately $5 billion to $6 billion in ex-factory sales, excluding taxes, with retail sales exceeding $10 billion.
The category remains smaller than vaping and heated tobacco, leaving room for further consumer penetration.
Product convenience is another factor behind his growth outlook. Nicotine pouches are compact, portable and require no heating device. They produce no smoke and little noticeable odor, while allowing relatively discreet use.
Chen believes these characteristics may appeal to some nicotine consumers, particularly where convenience and discretion influence product choice.
Regulation could also affect the pace of growth. In some markets, rules governing nicotine pouches are less developed than those applying to vaping and heated tobacco, leaving companies more flexibility in product development and market expansion.
But the same characteristics that make nicotine pouches discreet may raise concerns about use by minors. Age verification, nicotine-content limits and marketing restrictions could all become areas of greater regulatory attention, with consequences for the category's future growth.
For vaping, Chen sees a different opportunity.
He expects the overall global market to grow at a mid- to high-single-digit rate, but believes the compliant segment could expand by more than 10% as enforcement against noncompliant products increases.
Chen estimates that noncompliant products may account for 70% to 80% of the global vaping market. If enforcement reduces their market presence, some consumer demand could shift toward legally marketed alternatives, allowing compliant businesses to grow faster than the overall category.
His estimates put the global lawful vaping market at approximately $5 billion in ex-factory sales. Including noncompliant products, he believes the broader market could reach around $20 billion at the ex-factory level and approximately $40 billion at retail.
For compliant vaping companies, changes in market share could create growth opportunities even if overall category expansion remains relatively modest.
Chen is more cautious about heated tobacco.
Unlike vaping and nicotine pouches, heated tobacco draws a substantial proportion of its consumers from conventional cigarettes. After years of conversion, the rate at which additional smokers switch to heated tobacco may be slowing.
At the same time, declining cigarette consumption in established markets could reduce the pool of smokers available to convert.
Industry concentration adds another challenge. According to Philip Morris International's (PMI) 2025 results, the company held approximately 76% of global heat-not-burn category volume, leaving competitors facing a substantial hurdle in gaining market share.
Japan Tobacco and British American Tobacco have also adjusted their heated tobacco product offerings and pricing in recent years.
Although Chen expects heated tobacco consumption volumes to continue rising, he warned that price competition could offset part of the resulting revenue growth.
The category's outlook will also depend on how aggressively major manufacturers invest in new products and compete for consumers.
Why tobacco companies command different valuations
CCB International's May 2026 report argued that advances in newer tobacco and nicotine technologies were changing the investment characteristics of the industry.
The report noted that tobacco companies had historically been viewed as investments in a so-called "sin industry." With the development of vaping, heating and oral nicotine technologies, the research team argued that investment in newer tobacco businesses could, from certain perspectives, also be viewed as investment in technologies intended to reduce tobacco-related harm.
When it comes to valuation, however, Chen does not treat next-generation tobacco businesses simply as technology companies.
"At the end of the day, tobacco companies are still consumer goods businesses," he said.
Investors therefore often compare tobacco companies with other consumer businesses, including spirits, beer and other alcoholic beverages.
These industries share certain characteristics, including government regulation, public scrutiny and pressure on consumption volumes in mature markets.
The expansion of smoke-free products, however, is creating differences in tobacco companies' growth prospects.
Traditional cigarette businesses continue to generate substantial cash flow, but face declining volumes in several major markets. Companies with rapidly growing smoke-free businesses may consequently attract higher expectations for long-term earnings growth.
Philip Morris International and British American Tobacco (BAT) illustrate the distinction.
Chen said PMI had traded at higher price-to-earnings multiples than BAT in recent years, citing Bloomberg data. He attributed the difference partly to investor expectations for PMI's heated tobacco business.
Smoore International represents another business model.
As a company focused on newer tobacco-related businesses, Smoore does not face the same direct drag from declining conventional cigarette sales. Although its financial performance has encountered challenges in recent years, expectations for growth in its newer businesses may support a relatively higher valuation.
CCB International also uses different valuation methods depending on companies' cash positions and business structures.
In its May report, the firm valued RELX Technology using enterprise value to earnings before interest, taxes, depreciation and amortization (EV/EBITDA), BAT using a price-to-earnings (P/E) multiple, and Smoore using a sum-of-the-parts (SOTP) approach.
Chen explained that the P/E ratio is generally a suitable starting point for valuing a profitable business.
For companies holding large cash reserves, however, a P/E multiple alone may not adequately distinguish the value of financial assets from that of the operating business.
RELX offers an example.
According to CCB International's May report, RELX held approximately RMB 15.7 billion in cash, cash equivalents, deposits and short- and long-term financial investments at the end of 2025.
That amount was equivalent to approximately 84% of the company's market capitalization used in the report's valuation.
CCB International considered RELX's substantial financial reserves, shareholder returns and potential acquisition requirements when selecting its valuation method. EV/EBITDA allowed the research team to assess the operating business separately from the company's cash position.
For Smoore, CCB International adopted a sum-of-the-parts valuation because its vaping, heated tobacco and medical businesses were at different stages of development and could not reasonably be assessed using a single earnings multiple.
According to the May report, Smoore's established vaping business had a mature earnings base, while its heated tobacco and medical businesses were at earlier stages.
The medical business had not yet generated revenue or profits at the time of the report and remained in an investment phase.
The research team therefore valued the individual business segments using different approaches before combining them into an overall company valuation.
Profitability also featured prominently in discussions at the September 25 NAS conference.
Jefferies analyst Andrei Andon-Ionita used PMI to examine how tobacco companies could expand newer product categories while maintaining earnings.
A chart using company data and Jefferies estimates showed PMI's group earnings before interest and taxes (EBIT) margin at 41.2% in 2015 and 42.0% in 2025. Jefferies projected that the margin could reach 47.4% by 2030.
Andon-Ionita argued that PMI's ability to preserve overall profitability while expanding its newer businesses gave investors reason to reassess the durability of the company's earnings.
For investors, the growing contribution of smoke-free products is therefore only part of the valuation question. Companies must also demonstrate that they can maintain or improve margins and continue generating cash returns.
The NAS discussion also examined what investors can do after acquiring shares in tobacco companies.
Pieter Vorster, chief executive of Hexis Capital Management, challenged the practice of institutional investors excluding tobacco companies entirely from their portfolios.
Selling shares changes ownership and voting rights, he argued, but does not necessarily change the underlying business.
Rather than relying solely on divestment, Vorster advocated remaining a shareholder and engaging companies through voting rights and dialogue with their boards on research investment, capital allocation, governance and product transition.
Hexis applies that approach through its proprietary Hexis Nicotine Transition Score (HNTS), which assesses tobacco and nicotine companies and feeds into the firm's valuation and portfolio-construction process.
For Hexis, investment decisions involve not only assessing a company's future earnings but also considering whether shareholders can influence its long-term strategy through active ownership.
How global tobacco groups and Chinese companies compete
Chen sees distinct competitive advantages among established multinational tobacco companies, Chinese technology suppliers and Chinese consumer-facing brands.
The major international tobacco groups benefit from extensive global distribution networks, long-established consumer data, and substantial research and financial resources.
They can introduce new products through existing distribution channels across multiple markets, while years of consumer research and regulatory experience support product development and commercial planning.
But their size and business structures also impose constraints.
Having operated for decades under strict regulation and faced major litigation and consumer compensation claims, multinational tobacco companies tend to take a cautious approach to product launches, marketing and brand communication.
Products that have been developed may still be delayed or withheld because of regulatory, reputational or other risks.
Their established cigarette businesses also remain major sources of profit, creating another consideration when deciding how quickly to expand smoke-free products.
Among Chinese companies in the newer tobacco and nicotine sector, Chen identifies two broad business models: technology and manufacturing suppliers serving brand owners, and companies operating their own brands and distribution channels.
Smoore is an example of the first group.
Through sustained research, manufacturing investment and cooperation with international brands, Chinese suppliers have developed competitive strengths in vaping technology and large-scale production.
Some supplier relationships have expanded beyond manufacturing into product development and regulatory applications, strengthening ties with brand customers.
Chinese technology companies are also exploring commercial arrangements beyond conventional contract manufacturing.
CCB International's May report described Smoore's cooperation with BAT on heated tobacco products, based on information provided by Smoore's management.
Unlike conventional vaping manufacturing arrangements, the heated tobacco products supplied under this model are not accounted for simply as finished goods sold to BAT.
Instead, Smoore receives technology licensing fees calculated as a percentage of BAT's heated tobacco product sales revenue.
The report projected that as sales of BAT's glo Hilo products increased, the arrangement could allow Smoore's revenue from this business to grow faster than shipment volumes.
The precise royalty rates and commercial terms have not been disclosed.
Under such an arrangement, a technology supplier's revenue becomes more closely linked to its brand customer's market performance rather than depending solely on the number of products shipped.
That model does not eliminate customer dependence.
Chen noted that suppliers remain exposed to the strategies and decisions of their brand customers. Even when a supplier has developed competitive technology or products, its financial performance may be constrained if a customer delays a launch or decides against expanding sales.
Chinese companies operating their own brands and distribution networks have different strengths. RELX Technology is one example.
Chen believes these companies gained experience in consumer behavior and market development during the rapid expansion of the vaping industry.
Some newer brand businesses have more flexible organizations and shorter decision-making processes, enabling them to respond more quickly to changing market conditions.
Companies with accumulated financial resources may also use acquisitions to enter overseas markets or expand their operations.
For Chen, another important distinction lies in how Chinese and multinational tobacco companies engage with regulatory systems.
He argued that major international tobacco companies do not interact with regulators solely as businesses subject to government oversight.
They also use industry associations, policy engagement and legal challenges to participate in discussions about rules and policies affecting their operating environment.
Having operated across multiple jurisdictions for decades, established tobacco groups have accumulated experience with different regulatory institutions and legal processes. In some circumstances, they have challenged regulatory decisions through litigation.
Chinese companies in the newer tobacco and nicotine sector, by contrast, have developed largely within China's tobacco monopoly system and related regulatory frameworks.
Although businesses can submit views and recommendations, their interaction with regulatory authorities differs from the practices of multinational tobacco companies operating across numerous markets.
As Chinese companies expand overseas, Chen believes they will need to develop experience not only in meeting local regulatory requirements but also in communicating with authorities, participating in industry organizations and handling legal and policy matters.
Established multinational tobacco groups have accumulated these capabilities over a longer period of international operations.
How regulatory risk changes earnings forecasts and valuations
Regulation influences both the ability of companies to bring products to market and the way investors estimate their future earnings and value.
Chen said regulatory and enforcement risks generally enter valuation models through two channels: adjustments to revenue and earnings forecasts, and changes in the valuation multiples assigned to a company.
He offered a hypothetical example.
An analyst might initially expect a company's revenue in a European market to grow by 15% annually over the next three years.
If regulations on vaping products were expected to tighten, the analyst might reduce the baseline annual growth forecast to 10%.
The lower revenue projection would then affect expected earnings and cash flow.
A second adjustment concerns the valuation multiple itself.
If an analyst had initially assigned a company a target P/E multiple of 25 times earnings, but developments in the United States or another major market suggested greater regulatory uncertainty, the analyst might apply a risk discount.
That could reduce the target multiple to 20 or 22.5 times earnings, depending on the assessment.
Conversely, a more favorable regulatory outlook could support stronger earnings forecasts or a higher valuation multiple.
These figures were hypothetical examples Chen used to explain valuation methodology, not forecasts for a specific company.
The United States vaping market provides a practical case for observing how regulatory developments may affect companies' prospects.
Chen believes the central question is whether enforcement can materially change the balance between compliant and noncompliant products.
But restricting unlawful products and expanding the supply of legally marketed alternatives must proceed together.
Even if noncompliant products disappear from some distribution channels, consumer demand will not necessarily transfer directly to compliant brands.
The outcome will depend on manufacturing capacity, retail distribution, product flavors and the consumer experience offered by legally marketed products.
Chen pointed to the large range of flavored noncompliant vaping products previously available in the United States. If those products face stronger enforcement but compliant companies cannot offer sufficiently competitive alternatives, the resulting demand may not shift as expected.
At the September 25 NAS conference, Bradley Tusk, founder and chief executive of Tusk Ventures, approached regulation from the perspective of venture capital.
Tusk said investors in highly regulated industries need to assess regulatory obstacles and opportunities alongside the quality of a founding team and its technology.
For the startups he discussed, navigating regulation was not something to address only after raising capital. It was part of developing the commercial opportunity and evaluating the investment itself.
Three areas to watch: U.S. vaping, nicotine pouches and industry consolidation
Chen identified three developments that could be particularly important for the global tobacco and nicotine industry over the next several years.
The first is regulatory enforcement in the U.S. vaping market.
He believes the key question is whether authorities can sustain action against noncompliant products while legally marketed alternatives become more widely available and better able to meet consumer demand.
If competitive conditions improve, compliant companies with strong products, brands and distribution capabilities could gain new opportunities for growth.
The second is nicotine pouches.
"Nicotine pouches could grow into a category at least comparable in size to vaping and heated tobacco," Chen said.
Whether that happens will depend heavily on how individual countries develop regulatory frameworks suited to the category.
Because nicotine pouches can be used discreetly, they may raise particular concerns about use by minors without detection.
Age-verification requirements, nicotine-content limits and marketing restrictions could all affect the category's future market size.
Chen argued that excessively loose regulation could create social problems, while overly restrictive policies could encourage the development of gray markets.
For nicotine pouches to grow sustainably, he believes the balance between consumer demand, regulatory oversight and public concerns will be important.
His third area of interest is mergers and acquisitions across the global next-generation tobacco industry.
The established multinational tobacco companies themselves emerged through successive rounds of mergers and acquisitions, Chen noted.
Although those groups continue to hold substantial advantages in scale and distribution, the newer tobacco and nicotine market remains relatively fragmented, with numerous brands, technology businesses and regional participants.
That fragmentation may leave opportunities for newer companies to expand.
As the different product categories develop, further acquisitions and consolidation could reshape the industry's competitive structure.
"We cannot rule out mergers and acquisitions creating new large companies in the next-generation tobacco market," Chen said.
For continuing coverage of global tobacco and nicotine capital markets, follow 2Firsts.
Disclaimer
This article is provided solely for professional research, industry discussion, and informational purposes. Any references to brands, companies, products, technologies, or policies are made for factual reporting and analytical purposes only, and do not constitute endorsement, recommendation, promotion, or advertising by 2Firsts.
Nicotine-containing products, including but not limited to cigarettes, e-cigarettes, heated tobacco products, and nicotine pouches, carry significant health risks. Readers are responsible for complying with all applicable laws and regulations in their respective jurisdictions, including age restrictions and access limitations.
The information contained in this article should not be regarded as investment, legal, medical, regulatory, or commercial advice. While 2Firsts strives to ensure the accuracy and reliability of its content, it does not assume liability for any direct or indirect loss arising from errors, omissions, inaccuracies, or reliance on the information contained herein.
This article is not intended for individuals below the legal age for accessing tobacco or nicotine-related information in their jurisdiction.
Copyright Notice
This article is either original content produced by 2Firsts or content reproduced, translated, summarized, or adapted from third-party sources with attribution where applicable. The intellectual property rights of the original content remain with 2Firsts or the respective original rights holders.
No individual or organization may copy, reproduce, distribute, republish, modify, translate, or otherwise use this content without prior authorization. Any unauthorized use may result in legal action.
For copyright-related inquiries, corrections, or removal requests, please contact: info@2firsts.com.
AI-Assisted Translation and Editing Notice
Portions of this article may have been translated, edited, or reviewed with the assistance of artificial intelligence tools to improve efficiency and readability. Due to the limitations of AI-assisted translation and editing, discrepancies, omissions, or inaccuracies may exist when compared with the original source.
Where applicable, readers are advised to refer to the original source for the most complete and accurate information. If you identify any errors or believe that any content infringes upon your rights, please contact us at info@2firsts.com, and we will review and address the matter promptly.