Key Points
- Quarterly Results: Third-quarter revenue rose 11.1% to $99.8 million, adjusted EBITDA increased 7.7% to $30.9 million, and net profit rose 13.8% to $7.6 million.
- Nine-Month Performance: Revenue reached $306.7 million, up 6.0%, while AIR swung to a $74.2 million net loss from a $38.7 million profit a year earlier, affected by listing-related costs.
- New Growth Categories: NGC generated $2.1 million in nine-month revenue, down 2.6%, and an adjusted EBITDA loss of $10.8 million, narrowing from $13.2 million a year earlier.
- Regional Operations: Third-quarter shisha revenue rose 25.6% in the Americas, 9.4% in the Middle East, Africa and Asia, and 4.9% in Europe.
- Outlook and Investment: AIR maintained its 2026 revenue growth guidance of 4%–6%, reduced its capex outlook and raised its expected year-end leverage ratio to approximately 2.5 times. Crown Switch's U.S. PMTA has been submitted, but marketing authorization has not been granted.
2Firsts
November 13, 2026
AIR Global PLC (NASDAQ: AIIR), whose core business is flavored shisha tobacco sold under the Al Fakher brand, reported an 11.1% increase in third-quarter 2026 revenue to $99.8 million on November 12. Adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) rose 7.7% to $30.9 million, supported by recovering shisha shipments and improved pricing and product mix.
For the first nine months of 2026, revenue increased 6.0% to $306.7 million. AIR, however, recorded a net loss of $74.2 million, compared with a $38.7 million profit a year earlier, as listing and business-combination expenses affected its reported results.
Its New Growth Categories (NGC) business, which includes vaping, nicotine pouches and other inhalation products, remained loss-making. Nine-month NGC revenue totaled $2.1 million, with an adjusted EBITDA loss of $10.8 million.
AIR reaffirmed its 2026 revenue growth guidance of 4%–6%, but lowered its capital expenditure outlook to $11 million–$14 million and raised its expected year-end net debt-to-adjusted EBITDA ratio to approximately 2.5 times from 2.1 times previously.
Q3 Revenue Rises 11.1% as Nine-Month Results Swing to $74.2 Million Loss
AIR's third-quarter revenue increased to $99.8 million from $89.8 million a year earlier.
The company attributed the growth to a 5.8% increase in flavored shisha molasses (FSM) shipment volumes and a positive contribution of approximately 5.0% from pricing and product mix.
Gross profit rose 9.8% to $53.2 million, while gross margin narrowed to 53.3% from 54.0%.
Cost of sales increased 12.7% to $46.6 million, reflecting higher logistics, raw-material and manufacturing-footprint costs.
Quarterly net profit increased 13.8% to $7.6 million. Adjusted EBITDA rose 7.7% to $30.9 million, although the adjusted EBITDA margin declined to 31.0% from 31.9%.
For the first nine months, AIR generated $306.7 million in revenue, up 6.0%, even as FSM shipment volumes declined 4.6%. A positive 11.1% contribution from pricing and product mix offset the volume decline.
Nine-month gross profit increased 4.6% to $170.0 million, with gross margin declining to 55.4% from 56.2%.
Under International Financial Reporting Standards (IFRS), AIR recorded a $74.2 million net loss for the period, compared with a $38.7 million profit in the same period of 2025. Adjusted EBITDA increased 2.3% to $102.7 million.
The company disclosed several expenses associated with its listing and business combination, including approximately $47.7 million in transaction-related fees and a separate $48.2 million noncash accounting charge related to equity issued at the business-combination date.
Its adjusted EBITDA reconciliation also listed $14.1 million in share-based compensation, $10.5 million in public-company readiness costs, $4.3 million in extraordinary costs linked to regional supply-chain disruptions and approximately $3.4 million in U.S. PMTA-related regulatory expenses.
These items have different accounting and cash-flow treatments and are presented separately in AIR's financial disclosures.
Americas Revenue Grows 25.6% as Supply Costs Continue to Pressure Margins
AIR continues to generate the majority of its revenue from flavored shisha tobacco.
Third-quarter FSM revenue in the Americas rose 25.6% to $21.9 million, driven by a 28.5% increase in shipment volumes. Adjusted EBITDA in the region declined 3.6% to $7.8 million, reflecting higher cost of goods sold.
Revenue in the Middle East, Africa and Asia (MEAA) increased 9.4% to $64.1 million, with volume growth of 3.0% and a positive price-and-mix contribution of 6.2%. Regional adjusted EBITDA rose 2.4% to $25.1 million.
European revenue grew 4.9% to $13.8 million, with adjusted EBITDA of $0.9 million compared with approximately breakeven a year earlier. AIR said higher excise taxes and insufficient enforcement against illicit products continued to affect the region.
For the first nine months, MEAA revenue reached $200.8 million, up 5.7%, remaining AIR's largest geographic business.
Chief Executive Stuart Brazier said shipment activity continued to recover during the third quarter following supply-chain disruptions in the first half, while logistics and material costs remained elevated because of geopolitical conditions.
Disruptions around the Strait of Hormuz affected shipments earlier in 2026, prompting alternative routing and changes to manufacturing and procurement arrangements.
AIR expects its new Romanian manufacturing facility to begin operating in the first quarter of 2027, further diversifying its production footprint.
New Growth Revenue Totals $2.1 Million as Crown Switch Enters U.S. PMTA Process
AIR's New Growth Categories segment includes vaping products, nicotine pouches and other inhalation devices.
Revenue from the segment totaled $2.1 million during the first nine months of 2026, down 2.6% year over year. Its adjusted EBITDA loss narrowed to $10.8 million from $13.2 million in the same period of 2025.
Third-quarter NGC revenue was negative $0.1 million, compared with positive revenue of $0.6 million a year earlier. AIR attributed the result to the timing of trade incentives rather than negative physical sales volumes.
The segment's quarterly adjusted EBITDA loss narrowed to $2.9 million from $3.9 million. The company cited lower operating costs and more focused investment in new product launches.
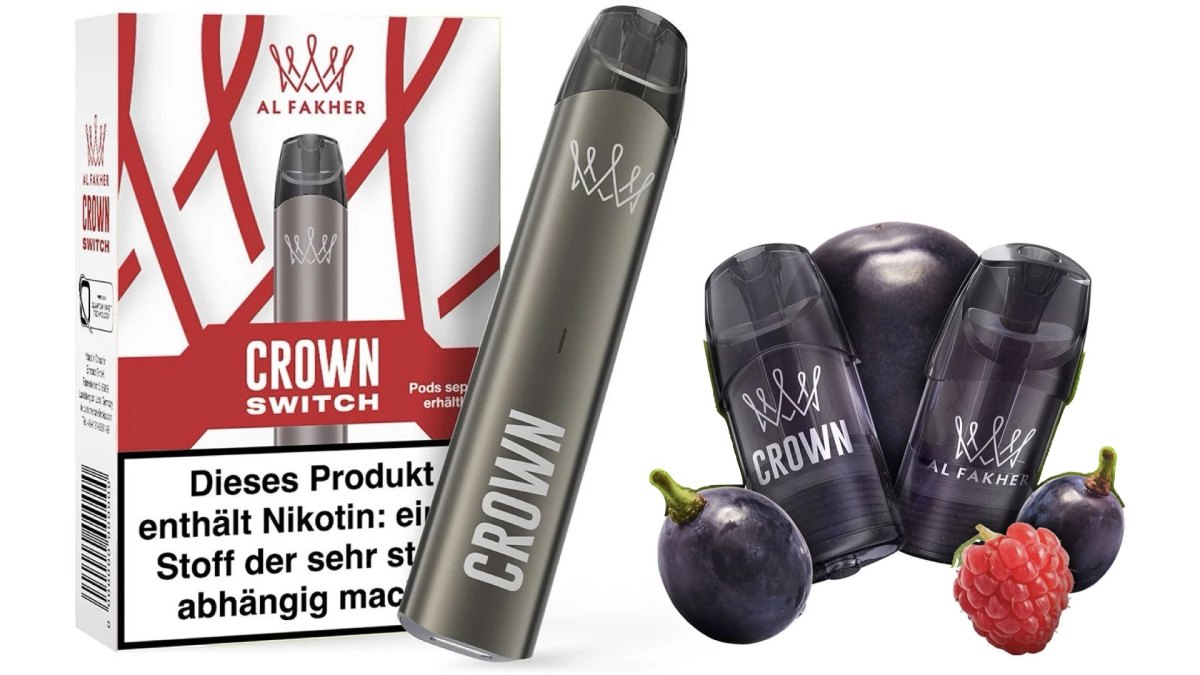
On November 5, AIR announced that it had submitted a Premarket Tobacco Product Application (PMTA) to the U.S. Food and Drug Administration (FDA) for Crown Switch, its rechargeable pod vape.
Crown Switch uses Quantum Chip atomization technology developed by Canadian vaping technology company Greentank. In July 2026, AIR announced a $20 million investment in Greentank, securing an equity interest, further investment rights and technology and long-term supply arrangements.
AIR disclosed approximately $3.4 million in regulatory expenses during the first nine months, primarily related to consulting, advisory and research activities supporting U.S. PMTA preparation and submission. The figure does not represent all development costs for Crown Switch alone.
As of November 13, AIR had not announced an FDA marketing authorization for Crown Switch.
The company said the timing and scale of revenue and adjusted EBITDA contributions from NGC in 2027 would depend on progress in the FDA's review of its PMTA applications.
In a shareholder letter published with the results, AIR said it is currently prioritizing U.S. vaping over nicotine pouches, citing its relative resource constraints, previous vaping licensing experience and management's expectations for profitability across different nicotine categories.
AIR Maintains 2026 Revenue Outlook but Cuts Capex and Raises Leverage Forecast
AIR reaffirmed its outlook for U.S.-dollar revenue growth of 4%–6% in 2026 and low- to mid-single-digit adjusted EBITDA growth.
The company expects FSM shipment volumes to be broadly stable compared with 2025. Weaker global travel retail activity linked to the Middle East conflict is expected to reduce full-year shipment volumes by approximately 1.5%.
AIR reduced its 2026 capital expenditure forecast to $11 million–$14 million from $15 million–$18 million previously.
The company also raised its expected year-end net debt-to-adjusted EBITDA ratio to approximately 2.5 times from an earlier forecast of 2.1 times, citing bond-issuance cash flows and the timing of working-capital movements associated with supply-chain disruptions.
At September 30, AIR reported net debt of $364.8 million, equivalent to 2.6 times trailing 12-month adjusted EBITDA.
On October 1, AIR completed a $425 million senior unsecured notes offering carrying a 7.875% coupon and maturing in 2031. The proceeds were used to refinance existing term-loan and revolving-credit arrangements.
AIR continues to target net debt to adjusted EBITDA of no more than 2.0 times by the end of 2027.
The company has outlined plans to begin paying an annual dividend of $0.28 per share in 2027 and to undertake up to $100 million in share repurchases through December 2029, subject to cash generation, market conditions and relevant approvals.
AIR said it will continue reviewing capital allocation across its businesses. Some investments may be deferred, reduced or discontinued, potentially resulting in impairment charges or write-offs.
Its near-term operating priorities include recovering shisha shipment volumes and margins, adjusting manufacturing and logistics operations, and progressing regulatory applications and commercialization across its New Growth Categories business.
Follow 2Firsts for developments in global tobacco and nicotine companies, financial results, product commercialization and corporate investment.
Cover Image:Air